 US – English
 UK – English
 Canada – English
 Australia – English
 Danmark – Dansk
 DACH - Deutsch
 France – Français
 España – Español
 Sverige – Svenska
 Italia – Italiano
 Nederland – Nederlands
 Portugal – Português
 Suomi – Suomi
 Norge – Norsk
 日本 – 日本語
 Romanian – Română



How much does a financial advisor cost in 2026? Fees, rates & tax rules
Run your entire firm on one platform
Key takeaways:
- Most advisors charge a percentage of the assets they manage, with rates declining as your portfolio grows.
- On a $500,000 portfolio, a 1% fee costs roughly $86,000 over 10 years and $292,000 over 20 years in fees and missed growth.
- Investment advisory fees are permanently non-deductible for individual taxpayers after the One Big Beautiful Bill Act.
- A traditional IRA can pay its own advisory fee with pre-tax dollars without triggering a taxable distribution.
- Fee-only advisors earn no commissions from product sales. Fee-based advisors may. The distinction matters.
Financial advisors often charge about 1% of assets under management (AUM) per year, but you may also get quoted hourly rates of $200+ or flat annual fees. Then you’ve got robo-advisors that typically charge between 0.25% and 0.50% of assets per year.
So, we’ve already got several service types and pricing models to consider, but what do the numbers really mean if you’re looking for a financial advisor? To answer this question, let’s break down the major models, show what the 1% AUM fee costs over 10+ years, and discuss the other factors that determine the full cost of a financial advisor.
Table of сontents
- How much does a financial advisor cost in 2026?
- How financial advisors charge
- What a 1% fee really costs over time
- Are financial advisor fees tax-deductible in 2026?
- What affects the cost of a financial advisor?
- Robo-advisor vs human advisor vs CPA firm with planning
- How to check what you’ll actually pay
- Is a financial advisor worth the cost?
- FAQs
How much does a financial advisor cost in 2026?
The cost depends on the fee model your advisor uses. Here is an at-a-glance breakdown of the most common structures.
| Fee model | Typical cost | Best for |
| AUM percentage | About 1% per year on portfolios up to $1M; declines on larger balances | Ongoing investment management and comprehensive planning |
| Hourly | $200–$400 per hour | One-off consultations, plan reviews, or specific questions |
| Flat annual retainer / subscription | $2,500–$9,200 per year (median $4,500) | Year-round planning and access to your advisor |
| One-time financial plan | About $3,000 (median) | A standalone roadmap without ongoing management |
| Commission-based | Varies by product (typically 1%–8%) | Insurance or annuity purchases (note potential conflicts of interest) |
| Robo-advisor | 0.25%–0.50% per year | Hands-off, algorithm-driven investing at a lower cost |
The most common model is a percentage of assets under management, used by 92% of advisors according to the 2024 Kitces Research. Hourly and retainer ranges come from NerdWallet’s fee guide. Each model is explained in full below.
How financial advisors charge
Percentage of assets (AUM)
If you meet with a financial advisor, the fee you are most likely to be quoted is a percentage of your portfolio. Most advisors use a graduated schedule: the first $1 million is charged at one rate (commonly 1%), and each tier above that is charged at a lower rate.
Here is a simplified example. On a $1.5 million portfolio with a graduated 1%/0.80% schedule, the annual fee would be $10,000 on the first $1 million plus $4,000 on the remaining $500,000, for a total of $14,000, or a blended rate of about 0.93%.
Hourly
This model suits people who need help with a specific question or a one-time review, such as evaluating a pension buyout, reviewing an estate plan, or getting a second opinion on existing investments. You pay only for the time you use, and the typical rate range is in the table above.
Hourly engagements work well when you have a defined question and do not need ongoing management. The trade-off is that the advisor will not be monitoring your situation between sessions or reaching out proactively when something changes.
Flat annual retainer or subscription
Flat-fee advisors charge a set dollar amount each year regardless of your portfolio size. The typical range and median are in the table above, and the median has risen meaningfully since 2022 as more firms adjust pricing to reflect the full scope of planning work involved.
These arrangements typically include ongoing financial planning, investment management, tax coordination, and regular check-ins. For larger portfolios, a flat fee can work out to significantly less than a percentage-based charge.
One-time financial plan
The median cost for this type of engagement is in the table above. What you get for that fee is a written plan covering retirement projections, tax strategies, insurance needs, and estate planning, without ongoing management.
This option makes sense if you want a professional roadmap but do not need someone managing your portfolio on an ongoing basis. The plan is yours to implement, and the advisor’s involvement typically ends once the document is delivered.
Commissions
Commission-based advisors earn money from the financial products they sell you. The rates vary by product type:
- Mutual fund sales loads: Front-end loads on Class A shares are typically around 5% to 5.75% of the investment. FINRA caps the maximum sales charge at 8.5%.
- Annuities: Commissions are built into the contract price and generally range from 1% to 8% of the contract value, with longer-term fixed-indexed annuities at the higher end.
- Life insurance: First-year commissions can run 50% to 100% of the annual premium, with smaller renewal commissions in subsequent years.
The key concern: because the advisor’s income depends on which products they recommend, commissions can create conflicts of interest.
If you want to rule out commission-driven advice, confirm that your advisor is fee-only, meaning they receive no compensation from product sales. A fee-based advisor charges client fees but may also earn commissions on certain products, which can influence what they recommend. Asking this question before you sign anything is one of the simplest ways to protect yourself.
What a 1% fee really costs over time
A 1% annual charge may sound small, but it compounds against you the same way investment returns compound in your favor.
The table below is illustrative. It assumes a $500,000 starting portfolio, a 6% annual return, and the fee deducted at the end of each year, before taxes.
| After 10 years | After 20 years | Lost to fees and missed growth (10 yrs) | Lost to fees and missed growth (20 yrs) | |
| No fee | About $895,000 | About $1.60M | — | — |
| 1% AUM fee | About $810,000 | About $1.31M | Roughly $86,000 | Roughly $292,000 |
| $4,500 flat annual fee | About $836,000 | About $1.44M | Roughly $59,000 | Roughly $166,000 |
One important caveat: flat-fee and AUM advisors don’t always provide the same scope of service. This comparison illustrates the mechanics of different fee structures, not a direct value-for-value matchup. A 1% fee may be well worth it if it includes comprehensive tax planning, estate coordination, and behavioral coaching that a flat-fee arrangement does not.
Are financial advisor fees tax-deductible in 2026?
No. The Tax Cuts and Jobs Act removed the deduction for investment advisory fees starting in 2018, originally through 2025. The One Big Beautiful Bill Act made that removal permanent for tax years beginning after December 31, 2025. There is no way to deduct your advisory fee on your personal tax return in 2026, regardless of your income or the fee structure.
There is, however, one notable workaround.
A traditional IRA can pay its own advisory fee
If your advisory fee is paid directly from a traditional IRA, that payment is not treated as a taxable distribution. The legal basis is Treasury Regulation 1.404(a)-3(d). Because a traditional IRA holds pre-tax dollars, paying the fee from within the account means the fee is effectively paid with pre-tax money.
Example: You have a $250,000 traditional IRA subject to a 1% advisory fee ($2,500). Your advisor bills the IRA directly for the portion of the fee attributable to that account. You pay $2,500 with pre-tax dollars, and no taxable distribution is triggered.
Roth IRA fees: pay from an outside account
The opposite logic applies to a Roth IRA. Roth accounts grow tax-free, so every dollar that leaves the account is a dollar of tax-free growth you can’t replace. If you have the cash available, it is generally better to pay Roth IRA advisory fees from a taxable account rather than pulling from the Roth itself.
Never pay one account’s fees from another
Paying the advisory fee for a taxable or Roth account out of a traditional IRA can trigger a taxable distribution, early-withdrawal penalties (if you are under 59½), or even risk disqualifying the account. Each account should pay only the fee attributed to it.
Because these rules interact with your broader tax picture, coordinating with your CPA matters here. That is one reason some people choose a CPA firm that also offers financial planning, so their tax advisor and financial advisor are looking at the same numbers.
What affects the cost of a financial advisor?
- Portfolio size. Fees are often graduated, meaning the percentage declines as your assets grow. Many firms also have account minimums that can range from $50,000 to $500,000 or more.
- Scope of services. Investment management alone costs less than comprehensive planning that includes tax strategy, estate work, and insurance analysis.
- Credentials. Advisors with advanced designations like CFP (Certified Financial Planner) or CPA/PFS (Personal Financial Specialist) bring broader expertise across tax, estate, and financial planning.
- Fiduciary duty. A fiduciary is legally required to act in your best interest. Not all advisors are fiduciaries. Confirming this before you hire someone is one of the most important steps you can take.
- Location. Advisors in major metropolitan areas tend to charge higher rates than those in smaller markets.
- Hidden costs. The advisor’s fee is not the only cost. The funds inside your portfolio carry their own expense ratios, and some custodians charge trading fees. Always ask about the total cost, not just the advisory fee alone.
Robo-advisor vs human advisor vs CPA firm with planning
The right option depends on the complexity of your finances, how much guidance you need, and how involved you want to be.
| Option | Typical cost | What you get | Best for |
| Robo-advisor | Fraction of what a human advisor charges (see fee table above) | Algorithm-driven portfolio management, automated rebalancing, and basic tax-loss harvesting | People with straightforward investments who want a low-cost, hands-off approach |
| Human financial advisor | Percentage of assets, hourly, or flat retainer (see fee table above) | Personalized investment management, retirement planning, insurance analysis, estate coordination, and behavioral coaching | People with complex finances, multiple goals, or significant life changes |
| CPA firm with financial planning | Varies (typically a planning fee or AUM fee on top of existing tax services) | Tax-integrated financial planning from the firm that already prepares your taxes, with visibility across your full financial picture | People whose financial decisions are tightly linked to their tax situation and who want one team handling both |
The CPA-firm option is worth knowing about because it combines tax preparation and financial planning under one roof. Your tax advisor already sees your full income picture, deductions, and entity structures, which means the planning advice can be tightly coordinated with your tax strategy. This does not mean it is inherently cheaper or better than the other options; it means the integration can reduce the chances of advice falling through the cracks between two separate professionals.
How to check what you’ll actually pay
Before signing with an advisor, run through this short checklist.
- Ask for the firm’s Form ADV Part 2A. Section 5 lists every fee type the firm charges. You can find this document for free through the SEC’s Investment Adviser Public Disclosure search. Also check FINRA BrokerCheck for any disciplinary history.
- Ask for the total cost, not just the advisory fee. Your advisor’s fee is one layer. Fund expense ratios, platform fees, and trading costs sit on top of it. Ask for an estimate of the full annual cost on your portfolio size.
- Get the fee schedule in writing. Confirm the percentage, any graduated tiers, account minimums, and whether the fee is billed in advance or in arrears. If the advisor uses a flat fee, confirm exactly what services are included and what costs extra.
Is a financial advisor worth the cost?
It depends on your situation. Here is a simple way to think about it.
A financial advisor is likely worth the cost when your finances are complex (multiple income sources, equity compensation, business ownership), when a major life or business event is approaching (retirement, selling a company, divorce, inheritance), or when you simply do not have the time or interest to manage your money and tax strategy yourself.
A financial advisor may not be necessary yet if your savings are relatively simple, your portfolio is small, and your tax situation is straightforward. In that case, a robo-advisor or an occasional hourly consultation may be enough until your needs grow.
Vanguard’s Advisor’s Alpha research (updated September 2025) estimates that implementing a framework of wealth management best practices can add up to 3% in net returns for clients, with the biggest gains coming from keeping clients on course during market downturns. This is an industry estimate produced by a firm that works with advisors, and the actual value depends on the specific advisor and client. The value is real for the right match, but it is not automatic.
For a deeper look at what to evaluate before hiring, see our guide to how to choose a financial advisor.
FAQs
What is the average fee for a financial advisor?
About 1% of assets under management per year on portfolios up to $1 million, declining on larger balances. This is the most common fee structure, though hourly, flat retainer, and one-time plan options also exist depending on what you need.
Is 1% too much for a financial advisor?
Not necessarily. Whether that fee is justified depends on the scope of service you receive. If your advisor helps you avoid reactive decisions during downturns and coordinates your tax strategy alongside your investments, the fee may be justified. If you are paying for investment management alone and your needs are simple, a lower-cost alternative may be more appropriate.
How much does a one-time financial plan cost?
A comprehensive plan typically runs around $3,000. The price depends on scope: a plan focused on a single goal like retirement costs less than one covering retirement, tax strategy, insurance, and estate planning together. You receive a written roadmap without ongoing management, so this option works if you are comfortable implementing the recommendations yourself.
Are financial advisor fees tax-deductible in 2026?
No. The suspension of this deduction, originally temporary under the Tax Cuts and Jobs Act, became permanent in 2026. Advisory fees cannot be deducted on an individual tax return regardless of income or fee structure.
Can I pay advisory fees from my IRA?
Yes. The IRA pays the fee directly, and because the account holds pre-tax money, the fee comes out of pre-tax dollars without triggering a distribution. For Roth IRAs, it is generally better to pay from a taxable account to preserve tax-free growth.
What’s the difference between fee-only and fee-based advisors?
The difference is where the money comes from. A fee-only advisor is paid exclusively by you. A fee-based advisor is paid by you and may also receive commissions from products they sell.
Can my CPA also be my financial advisor?
Yes. Some CPA firms offer financial planning and investment management alongside tax services. CPAs who hold the PFS (Personal Financial Specialist) credential are specifically trained to provide integrated tax and financial planning.
Knowing the fee model is the first step. Calculating the long-term cost is the second. Getting the fee schedule in writing before you commit is the third.
The professionals listed in the TaxDome Accountant and Advisor Finder all work through a secure client app rated 4.9 stars by 35,000+ clients, so you know before your first meeting how documents, messages, and payments will be handled.
Related reading: How much does a CPA cost? | How much does an accountant cost?
Aaron produces practical content for TaxDome, drawing on 11 years in SaaS copywriting and marketing. He helps accounting and tax professionals get the most from TaxDome and other tools, making complex topics clear and actionable.
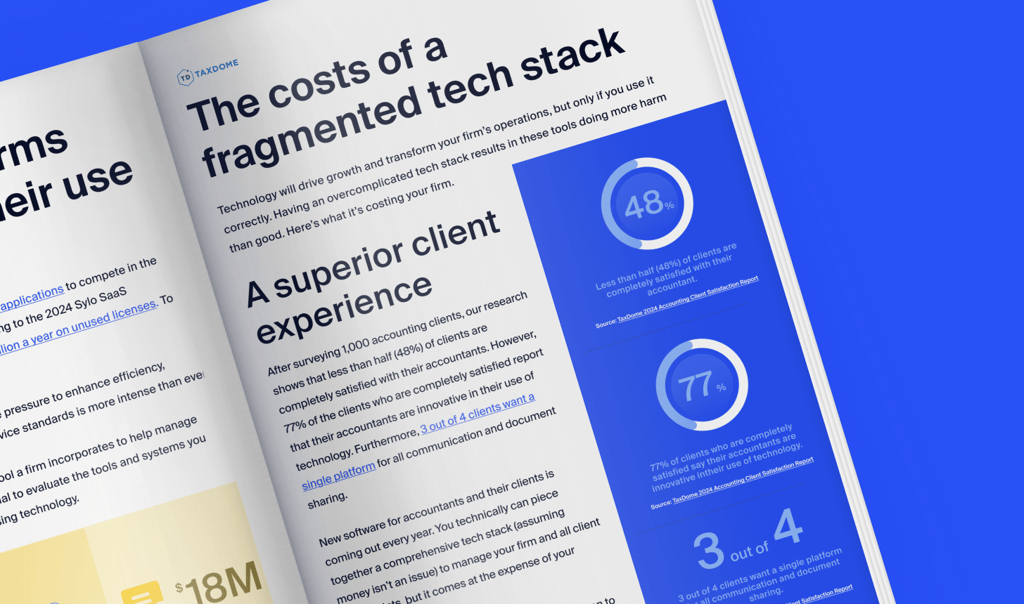
Get your free guide
Thank you!
The guide copy has been sent to your email. Please check your inbox!
Recommended articles
How much does it cost to outsource accounting? 2026 outsourced accounting pricing
How to start an accounting firm: a step-by-step guide to running your own practice
Accounting process improvement: Practical strategies, tools, and real-world examples